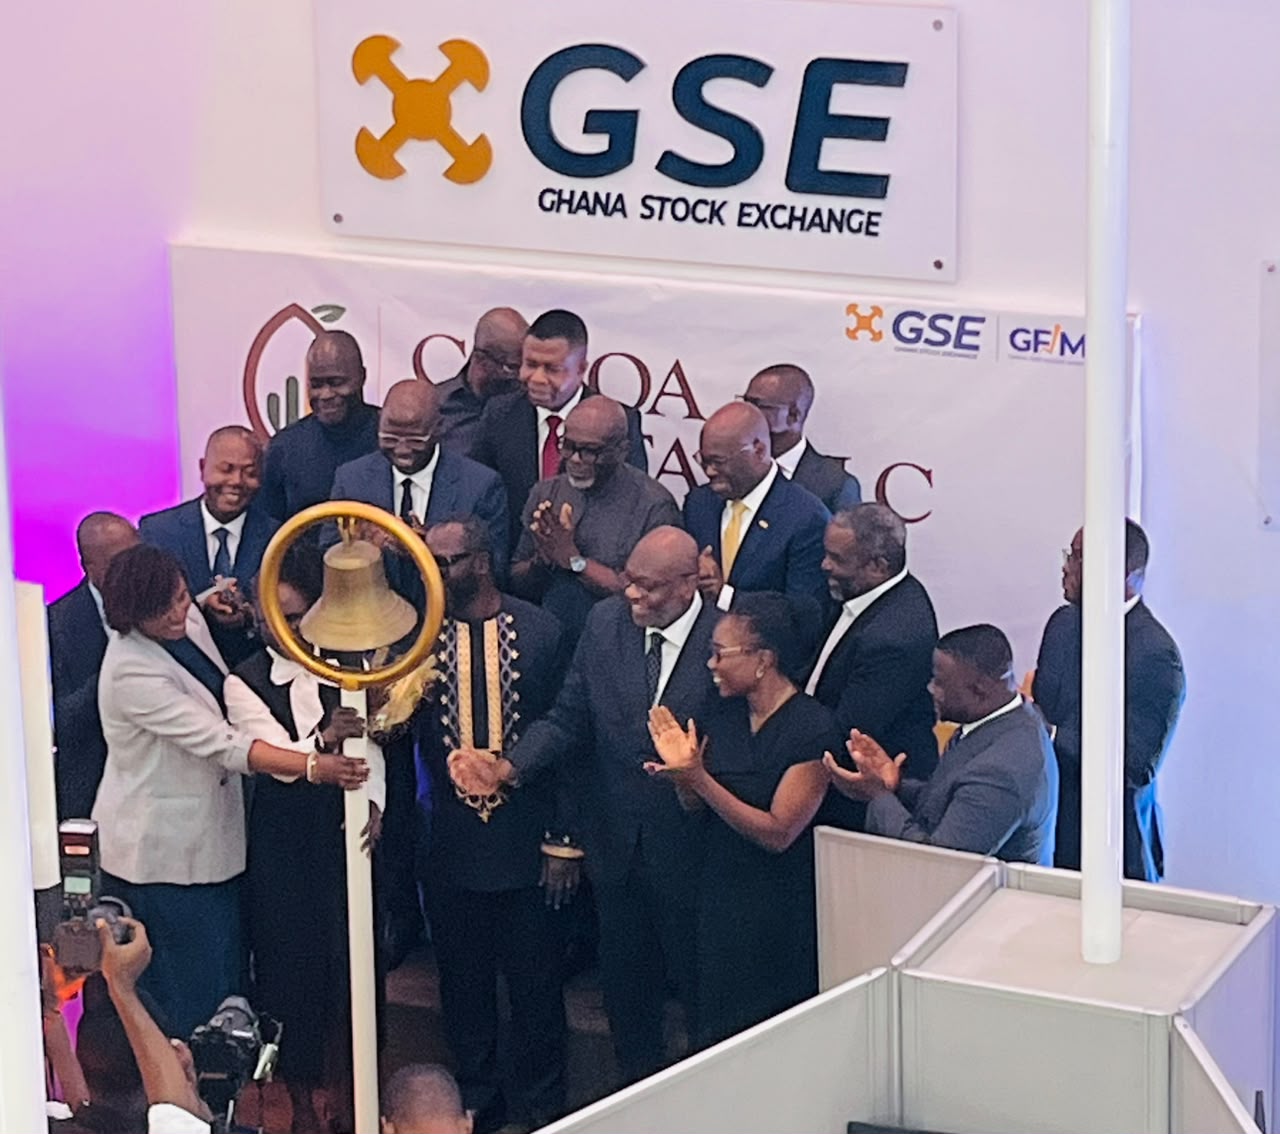
Ghana’s National Pensions Regulatory Authority (NPRA) has cautioned pension funds as their capital enters the GHS 16.3 billion cocoa financing market. The regulator insists that pension funds must not let ambition overshadow their primary duty to protect workers’ retirement assets.
This warning follows the admission of Cocoa Capital PLC’s Series 1, Tranche 1 commercial paper to the Ghana Fixed Income Market on October 14, 2026. The inaugural issuance attracted approximately GHS 3.59 billion in demand, raising GHS 3.39 billion. This strong interest highlights the capital market’s ability to mobilize significant funds for a strategic export industry.
The broader cocoa financing programme aims to raise GHS 16.3 billion, comprising GHS 14 billion in commercial paper and GHS 2.3 billion in bonds. This initiative seeks to channel domestic capital into cocoa purchases and create new investment opportunities for institutions managing savings pools. The NPRA’s intervention places a clear boundary around the enthusiasm generated by this new financial instrument.
Philemon Laar, Director of Planning, Research, Monitoring and Evaluation at the NPRA, delivered the authority’s message. He stressed that pension trustees manage deferred income belonging to workers, not their own money. Their first responsibility is fiduciary, meaning they must act solely in the best interest of the beneficiaries, rather than patriotic.
For pension schemes, high demand from other investors cannot replace independent analysis. A security, even if oversubscribed, may carry risks unsuitable for a particular fund’s liabilities, liquidity position, or exposure limits. The NPRA’s call for stronger investment discipline, regulatory compliance, and transparency directly addresses this concern.
Pension capital can finance various sectors like agriculture, housing, and infrastructure. However, each investment must be justified by expected return, credit quality, diversification, and the probability of repayment. The commercial paper, with an annual interest rate of 11 percent, matures on June 28, 2027, after 266 days.
Cocoa Capital’s structure includes safeguards, such as repayment supported by receivables from cocoa forward-sales contracts. Collections are directed through ring-fenced accounts, which are separate accounts designed to protect specific funds. This arrangement aims to create a visible cash-flow pathway connecting export proceeds to debt-service obligations, reducing the risk of diversion.
Despite these safeguards, the NPRA warns that ring-fencing cannot eliminate all risks. The underlying receivables remain exposed to production shortfalls, crop disease, ageing farms, and climate pressures. International price movements and operational execution also pose significant threats. Pension investors must evaluate the economic substance behind the structure, not just its legal framework.
Liquidity is another critical consideration. While the commercial paper matures in 266 days, fund managers must assess the existence of an active secondary market. They need to determine if their schemes could meet benefit payments or portfolio obligations if trading conditions become difficult before June 2027, preventing quick sales without substantial discounts.
Concentration risk is also important. If pension funds become major buyers across successive tranches, their exposure to one issuer, one commodity, and one financing model could rise rapidly. The full programme is almost five times larger than the inaugural issuance, potentially increasing this risk significantly.
Ghana’s recent domestic debt restructuring gives the NPRA’s warning additional weight. That episode demonstrated that even dependable instruments can be altered under fiscal or financial pressures. It also showed how correlated exposures can transmit one borrower’s difficulties across banks, insurers, pension funds, and households. While Cocoa Capital’s receivables-based structure offers different protections, the broader lesson about assessing risk remains applicable.